

C11000 cathode pricing has three layers (LME benchmark + regional premium + product-form conversion premium). This week was about Layer 1, not Layers 2 and 3. The paper market repriced; the physical market barely flinched.
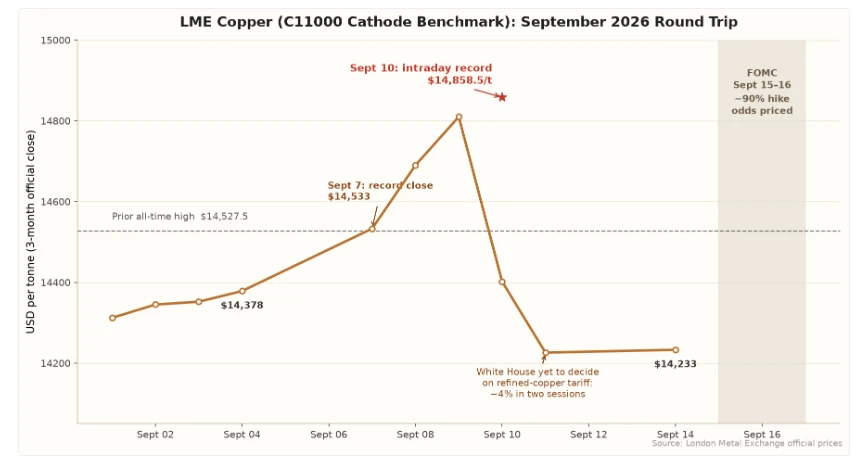
Source: London Metal Exchange official prices. Prior all-time high reference line at $14,527.5/t; FOMC shaded region covers the September 15–16 policy meeting.
The Week in Numbers
| Indicator | Latest reading | Move vs prior week | Note |
|---|---|---|---|
| LME 3-month copper (Sept 14) | $14,233 / tonne | -1.31% | First weekly loss since June |
| Intraday high (Sept 10) | $14,858.5 / tonne | New all-time record | Reversed within two sessions |
| LME cash | $14,238 / tonne | cash/3M in contango of -$10.38 | First time in six weeks |
| SHFE copper 2610 (Fri night) | 108,440 yuan / tonne | -0.20% on the night | Shanghai spot 1# avg 109,310 |
| SHFE weekly high (Sept 8) | 110,620 yuan / tonne | +7-month high | First time back above 110k |
| Spot copper-concentrate TC | -$209.7 / dmt | From -$200.31 | Smelter spot loss 3,580 yuan / tonne |
| Yangshan premium | $90 / tonne | Up from $85 | Cathode arbitrage window open |
| Import parity (cathode) | +618 yuan / tonne | From -722 (prior week) | Window open, but shipment space tight |
| LME warehouse stocks | 234,475 tonnes | -275 t | Cancelled-warrant share 49.8% |
| SHFE stocks | 54,780 tonnes | -13.05% week-on-week | Lowest since January 2024 |
| SMM domestic social inventory | 87,500 tonnes | Continued decline | Shanghai region 58,100 t |
| COMEX warehouse stocks | ~696,000 tonnes | +169 t (Sept 10) | 57 consecutive daily additions, record |
Two numbers in this table carry most of the story. The first is the spot treatment charge at -$209.7 per dry metric tonne, deeper into negative territory than at any point in the prior decade - a clear signal that mine supply is not keeping up with smelter demand. The second is the SHFE inventory draw of 13.05% in a single week, taking the visible Chinese stock to its lowest level since January 2024. Both of these point to the same conclusion: paper markets sold off because the macro narrative changed, but the physical market remains tight.
What Drove The Round Trip
Three forces acted in parallel to take the round trip off the table.
First, the tariff-relocation trade unwound. Most of the August and early-September rally was built on the assumption that the US would extend import duties to refined cathode, accelerating the transatlantic flow of copper into COMEX warehouses and tightening everything else. The wire-service report on September 10 made it clear that a decision was not imminent and that officials were weighing affordability concerns against the strategic case. The transatlantic-arbitrage narrative softened. COMEX-LME spread and premium structures compressed; the once-powerful incentive to redirect material to US shores is now being second-guessed by traders.
Second, the macro repriced hawkishly. The European Central Bank delivered a 25-basis-point rate increase on Thursday with a hawkish statement, ending any near-term hope of European easing. US core CPI for August printed 0.3% month-on-month versus a 0.2% consensus, and the year-on-year rate ticked up. The market quickly moved to price approximately a 90% probability of a Federal Reserve rate hike at the September 15–16 FOMC meeting, and a cumulative 53 basis points of additional tightening by year-end - the equivalent of two further 25-basis-point moves. Rising real yields and a stronger US dollar put consistent pressure on commodity prices in general, and copper was no exception.
Third, profit-taking met thin liquidity. LME copper had not had a down week since June. After touching the new intraday high, the position was crowded. When the news hit, the unwind was mechanical. Profit-taking amplified what was already a fundamentals-driven decline.
Why The Physical C11000 Market Barely Moved
This is the most important section for procurement teams. Despite the LME headline dropping more than 4%, three physical indicators all moved in the opposite direction.
Cathode premiums rose. The Yangshan bonded-warehouse premium (a clean read on Asian cathode scarcity) climbed from $85 to $90 per tonne. SHFE cash-to-3M, after spending most of August in a deep backwardation, is now flipping around a flat structure, but the SMM spot #1 cathode premium in Shanghai is still holding between 100 and 120 yuan per tonne for high-grade material, and the import arbitrage window is briefly open (positive +618 yuan per tonne for the first time in weeks). These are not signs of a market that is loosening.
Smelter economics are the worst in the cycle. With spot TC at negative $209.7 per dry tonne, the average Chinese smelter is losing approximately 3,580 yuan per tonne of refined output. That is below the cash cost of most secondary and high-cost primary smelters. Cut announcements from smaller Chinese smelters have been rising for months. Reduced refined output now is the natural response - which means tighter cathode supply next, not more of it.
The China-LME inventory split is widening, not narrowing. SHFE stocks fell 13% in a week to their lowest since January 2024. LME stocks are at 234,475 tonnes with 49.8% of warrants cancelled - a high ratio that signals metal is queued to leave the LME system rather than sit in it. The Chinese physical market is genuinely short of cathode, and the rest of the world is preparing to export more of what it has.
The Cash-3M Flip Matters
For the first time in six weeks, LME cash copper is trading below the 3-month price - by approximately $10 per tonne. This is a return to a mild contango, the standard market structure when nearby supply is comfortable and forward supply is expected to improve.
The change does not mean the market is suddenly well-supplied. It means the near-term spot squeeze that drove the August rally is easing. Inventories that had been locked into LME warehouses awaiting US shipment are now being released back into the European and Asian trade flows, simply because the tariff-driven incentive to hold them in the US has weakened.
The practical implication for C11000 cathode buyers: the days of paying $50–$80 per tonne premium for immediate-availability material are likely ending. If you can wait three to six weeks for delivery, your premium shrinks considerably. If you need material this month, expect to pay a still-elevated spot premium because domestic Chinese supply is genuinely tight.
The Week Ahead: Three Things To Watch
The September 15–16 FOMC is the single largest market-moving event for the rest of the month. Approximately 90% of the market is already pricing a 25-basis-point hike; the surprise would be either a larger move (50 basis points) or a hawkish forward statement that locks in additional tightening for the rest of 2026. Either outcome is bearish for non-interest-bearing commodities in the short term, but the downside may be limited given that a lot of tightening is already priced in.
The US tariff decision is the binary risk. A formal announcement extending duties to refined cathode would reignite the transatlantic trade immediately; a confirmation that cathode is exempt (or that the decision is being delayed further into the fourth quarter) would extend the recent selloff. Procurement teams with US-bound shipments should have a contingency plan for both outcomes.
Q4 demand starts to show in the data this week. September and October are when the seasonal AC, appliance, and wire-and-cable restocking builds in China and India. The first industrial production and retail sales prints for August will be released mid-month and will set the tone for whether the Q4 demand pull is real or has been priced in.
Procurement Recommendations For The Week
Use the contango to negotiate better terms on near-term shipments. LME cash is trading at a discount to 3-month; if you can accept a longer delivery window, your supplier has less reason to charge a premium for immediacy.
Keep the LME reference, not the absolute price, as the variable in your contracts. A pricing formula tied to LME plus a fixed conversion premium protects both sides from a continued selloff while preserving upside if the tariff story returns.
Re-verify the mill test certificate on every shipment. A weaker market is exactly when off-spec material shows up in the supply chain. A MTC confirming Cu content, oxygen level, and conductivity is the only document that proves you are buying C11000 and not a sub-grade substitute.
Lock your Q4 cathode volume this week. With smelter spot losses at 3,580 yuan per tonne and rising cut announcements, physical cathode availability is more likely to tighten than loosen between now and the Chinese New Year. The current LME weakness is a buying opportunity, not a signal to wait.
Have a tariff contingency plan for US-bound shipments. Talk to your supplier now about bonded-warehouse options, third-country transshipment, and origin documentation. If a tariff is announced between now and year-end, you do not want to be negotiating routing under deadline pressure.
Our C11000 Product Range
| Product form | Standard sizes | Temper range | Applicable standards |
|---|---|---|---|
| Copper tubes | OD 3–219 mm, wall 0.3–10 mm | O60, H55, H80 | ASTM B88, B280, B111; EN 1057, EN 12449 |
| Copper plates & sheets | Thickness 0.4–150 mm, width up to 3,000 mm | O60, H00, H02, H04 | ASTM B152, B187; EN 1652 |
| Copper bars & rods | Diameter 3–400 mm (round, square, hex) | O60, H02, H04 | ASTM B49, B133, B301; EN 12163 |
| Copper wires & rods | Diameter 0.05–12 mm | Soft and hard drawn | ASTM B1, B2, B3, B8; IEC 60228 |
| Copper strips & foils | Thickness 0.05–3.0 mm, width up to 620 mm | O60, H00, H02, H04, H06 | ASTM B36, B152; EN 1652 |
| Heat exchanger tubes | OD 6–57 mm, wall 0.4–4.0 mm | O60, H55 | ASTM B111, B359, B543; EN 12451 |
C11000 (Cu-ETP / T2) is the standard stock grade across our product range. For assemblies that require brazing, for marine or desalination service, or for higher-strength free-machining parts, we also supply C12200 (DHP), C14500 (tellurium copper), C18150 (chromium copper), and C46400 (naval brass) on request.
Request a C11000 Quote
Send your drawing, specification, and target quantity. We will return a fully itemized quote with LME reference, regional premium, and conversion premium itemized separately, plus mill test certificate confirmation.


